Search “buy now pay later apps NZ” and many lists still pair live services with providers that have closed or withdrawn. Zip has withdrawn from New Zealand, Genoapay and humm have closed, Laybuy is a legacy service within Klarna, and Payright says it is not issuing new loans.
That distinction matters at checkout. A listing for a discontinued service can send shoppers looking for a payment option they can no longer use, while businesses may spend time comparing or planning around unavailable providers.
This guide separates three options available for new purchases from five former providers and two features that are part of another service, not separate apps. For a wider comparison of instalment plans, see this payment plan app comparison.
The key is knowing which names are current, which are closed, and which are features.
Afterpay is still the closest thing to a default in New Zealand. It works across a wide spread of retailers, online and in store, and eligible customers split a purchase into four instalments over six weeks. The app handles the unglamorous essentials: finding retailers, tracking orders, showing what's due and when.
The mechanics are worth understanding properly, because they repeat across the category. New Zealand BNPL apps usually divide a purchase into fixed payments made weekly or fortnightly, and the provider may auto-deduct each instalment from your bank account, as Consumer Protection's buy now, pay later guidance explains. Miss one and a default fee can land. Some services add administration or payment-processing charges on top.
That's the honest version of "interest-free". On-time payments generally cost you nothing extra. Late ones do.
Practical rule: if you can't name your next three payday deductions without opening the app, you've got too many plans running.
What works: wide retailer coverage, one place to see payment dates, a stated cap on late fees. What doesn't: approval isn't guaranteed and limits vary by customer, missed payments can attract fees and may be reported to credit bureaus, and a credit enquiry can be visible to other lenders.
If you're wiring BNPL into a store of your own, our ecommerce payment platforms guide covers how it sits beside cards, bank transfer and wallets.
Website: Afterpay New Zealand
Klarna is the other name you'll see at New Zealand checkouts, and at some retailers it's the only alternative to Afterpay. The app pulls payment schedules, purchases, delivery tracking and returns onto one screen, which sounds like window dressing until you're chasing a refund across three browser tabs.
Pay in 4 is available at participating NZ merchants for eligible customers, and what you're offered depends on the retailer, the purchase and your approval. Klarna also acquired Laybuy's New Zealand assets in 2024, which is why the two names keep appearing in the same sentence in older articles.
BNPL isn't a niche habit here. The 2024 New Zealand Consumer Survey run by the Commerce Commission and MBIE found 37% of respondents had entered into a buy now, pay later agreement, across a sample of 2,363 consumers including 876 BNPL users. Use wasn't spread evenly: Māori and Pacific consumers, younger people and women were significantly more likely to have used it.
That's the argument for a second app. Not extra credit, but coverage. The shop you're buying from may only support one provider.
Pros: a genuine alternative where a merchant supports it, tidy order management, support in-app and by phone. Cons: merchant coverage differs from Afterpay's, pay-in-four isn't guaranteed, and leftover Laybuy branding at checkout causes genuine confusion.
If you're adding instalments to your own checkout, our payment processing solutions guide breaks down where BNPL fits.
Website: Klarna New Zealand
Finley works differently from pay-in-four apps such as Afterpay. It is an app-based revolving credit line from Pioneer Finance, a New Zealand provider, available at participating retailers. Eligible purchases have a published 60-day interest-free period.
After the interest-free period, interest applies to any remaining balance at a published 27.95% p.a. The minimum repayment is 3% or NZ$10, whichever is greater. Its published fee summary lists no sign-up or monthly account fee.
The repayment risk is worth weighing. MBIE's March 2024 Consumer Credit Research Report found that one quarter of New Zealanders who held credit in 2023 defaulted on a loan, and almost half reduced spending on important living expenses to avoid defaulting.
Finley may suit a larger purchase if you can clear it within the interest-free period. If you would need ongoing credit to make repayments, the interest rate can make the balance harder to manage.
Eligibility: approval requirements apply, and new applications aren't always open. How it decides: apps like this typically use an open banking connection to access transaction history. Before connecting an account, understand how open banking works in New Zealand.
Website: Finley
Zip is not a live option for new purchases in New Zealand. If you've landed here because you still owe money on a Zip plan, the useful part for you is further down, because hardship rules are the bit that still works.
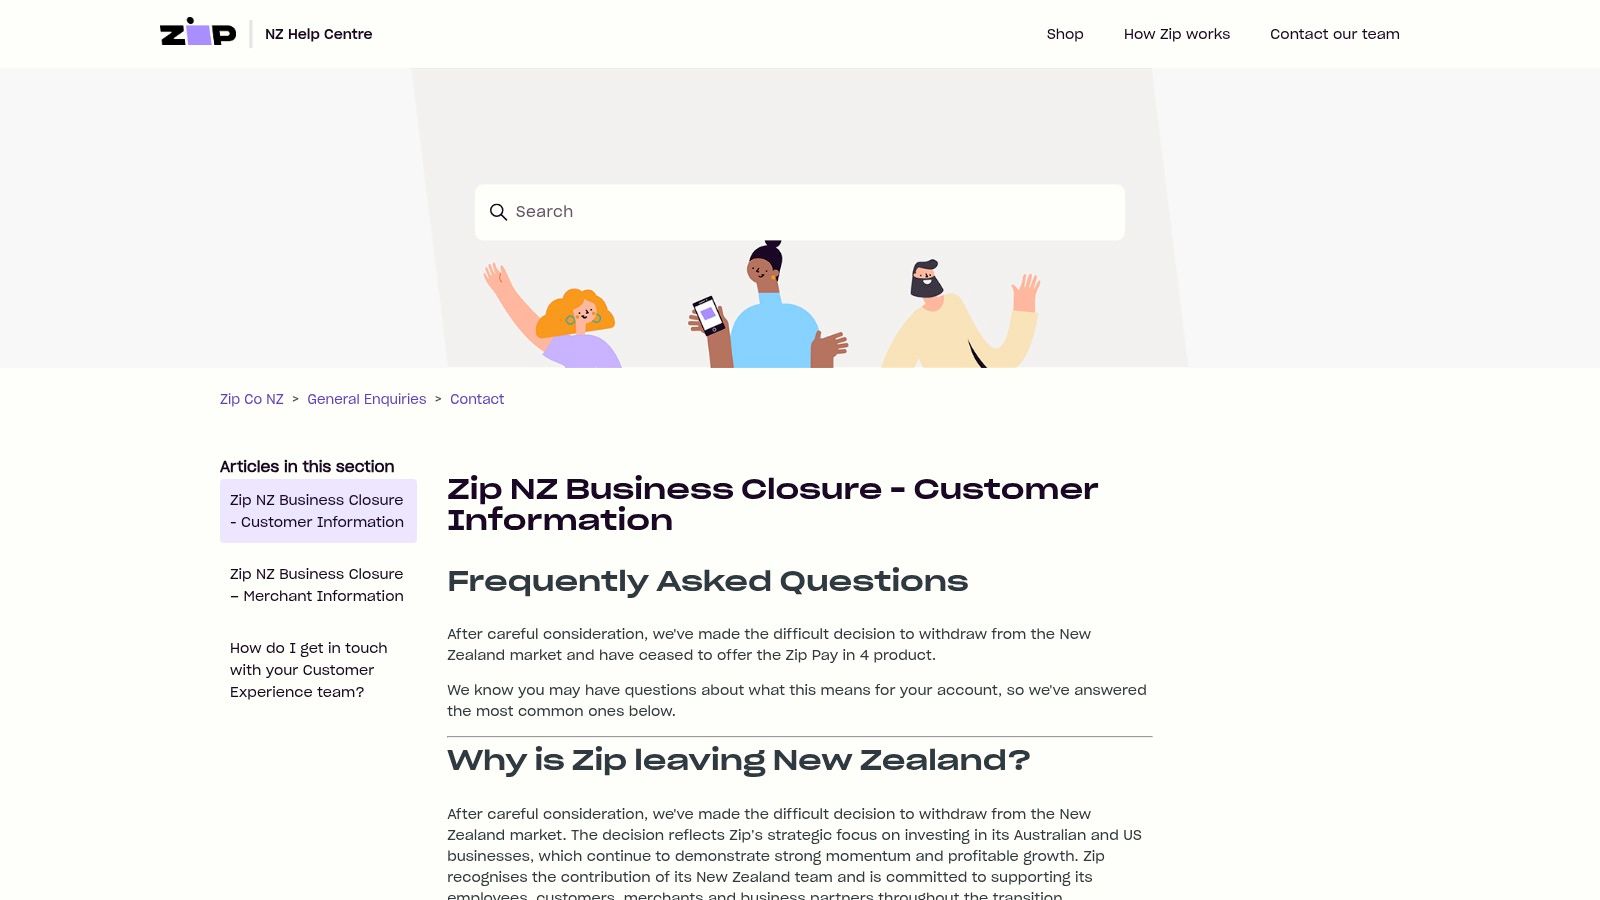
Zip previously ran a Pay in 4 product here and has announced its withdrawal from the NZ market. Existing customers may still get account-management access for outstanding balances. Account access isn't availability, though. Don't count Zip as a current alternative when you're comparing apps, and don't let an old bookmark convince you otherwise.
A New Zealand BNPL customer facing a real shock (job loss, serious illness, injury, a relationship breakdown) can apply in writing for a hardship change. You can ask for smaller repayments over a longer term, a payment holiday, or both.
Timing decides whether that option stays open. Consumer Protection's guidance on the Credit Contracts and Consumer Finance Act says you generally need to apply while less than two months behind on payments.
The clock afterwards is fixed. The lender must acknowledge the request within five working days, ask for more information within 10 if needed, and decide within 20. You get one application on the same grounds in any four-month period unless the provider agrees to another, and no fee can be charged just for considering it. A fee for changing the loan is possible.
Don't wait for the third missed payment. Hardship is a process with a deadline attached, not a favour you ask for once things are already broken.
Website: Zip NZ closure information
Payright's own New Zealand site settles it in a line. It no longer offers new loans. That's the whole status check done in ten seconds, which is more than most comparison pages will give you.
The company previously operated as a BNPL provider here. If you're an existing customer after information about a plan, the provider's site is the place to start, because it carries the current status rather than a paraphrase of it. If you're shopping this week, there's nothing here for you.
This is how exits usually look. A provider stops writing new loans, the site stays up, the brand keeps ranking, and the article you land on still lists it in a table of live options. The comparison sites don't update them. Nobody takes them down.
Ten-second test: open the provider's site and look for language aimed at new customers. If a page is clearly still selling but there's no way to start, that's your answer.
Useful for: confirming where an existing arrangement stands. Not useful for: anything you're buying in 2026.
One more thing worth saying out loud. A provider with no new lending isn't necessarily gone tomorrow, and a provider with new lending isn't necessarily safe. Availability and reliability are two separate questions, and the second one only shows up when something goes wrong.
Website: Payright NZ
Laybuy can still appear in NZ BNPL lists, but it is a legacy name, not a separate current option. Klarna acquired Laybuy's New Zealand assets in 2024, so check the payment option shown at checkout rather than relying on an old logo or article. If the retailer offers Klarna, use that option. If it doesn't, Laybuy isn't a separate route to payment.
New protections took effect on 2 September 2024. BNPL providers must follow many responsible-lending requirements under the Credit Contracts and Consumer Finance Act, while remaining exempt from some obligations that apply to conventional credit. The MBIE consumer protection guidance explains the current rules.
Those protections don't guarantee that every provider checks affordability in the same way. Credit-reporting arrangements have also been adjusted to accommodate BNPL data. Exactly what gets shared, and when a missed payment appears on a credit profile, can depend on the reporting arrangements.
Quick check: If you've used several BNPL providers, check your credit report to see what's being reported. No entry doesn't prove your record is clear, and an entry doesn't automatically mean it's been damaged.
Website: Klarna New Zealand (klarna.com/nz)
Genoapay closed in New Zealand on 11 April 2023. Not paused, not rebranded, not absorbed. Closed, with the closure information published by Gem Finance for anyone who wants to verify it.
Why does a dead service still rank? Because the NZ market grew while the number of providers shrank, and nobody went back to clean the archive. Demand didn't fall away when these brands left. It moved to whoever was still standing.
That's the pattern to hold onto. When a provider exits, its customers don't stop wanting instalments. They shift, usually to one of the two or three names that keep turning up at checkout. Which is why a list that ranks a closed app alongside a live one isn't just untidy. It's actively misleading about where your money is going.
Worth doing: search the provider's name plus "closure" before you sign up to anything unfamiliar. It takes a minute and saves an afternoon of dead ends.
Skip: any roundup that doesn't date its research. BNPL changes faster than most content gets refreshed.
Website: Genoapay closure notice
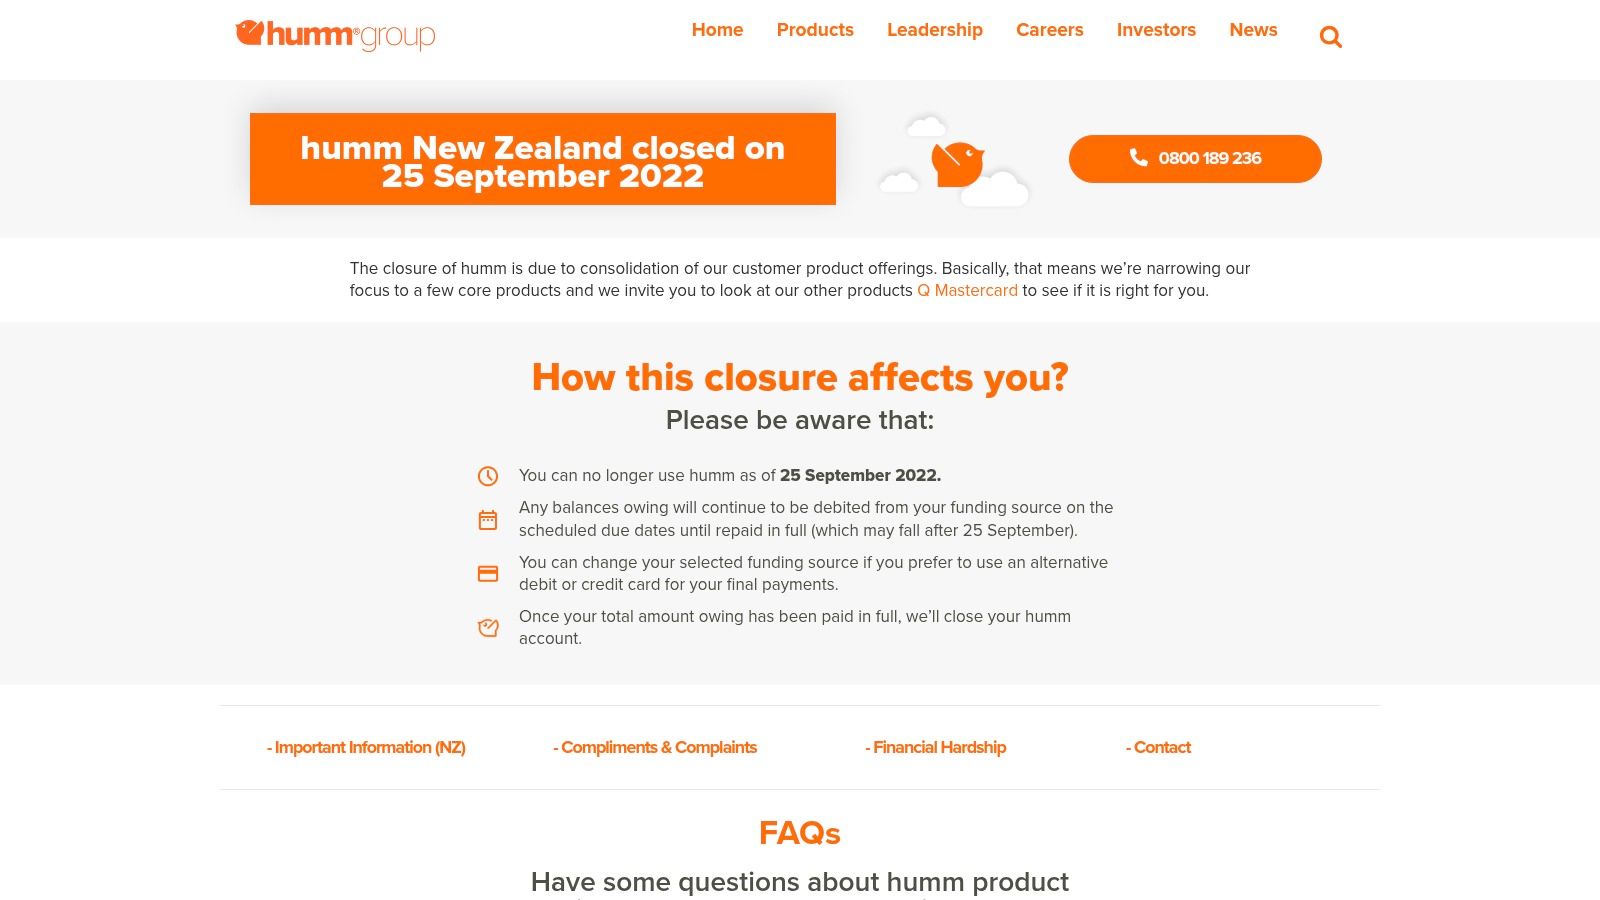
humm's New Zealand service closed on 25 September 2022, which makes it a former provider rather than a current option. The group's own closure page confirms it, and that's the fastest way to settle the question if an older comparison has you second-guessing.
I keep entries like this in a list on purpose. A closed option takes thirty seconds to rule out and hours to chase if you don't. You download the app, you start a sign-up, you get nowhere, and all the while the retailer you're buying from offers something else entirely.
The other reason is cleaner. If you held a humm plan, your questions are about balances and records, not about opening something new.
Three checks before you trust any BNPL listing:
Website: humm NZ closure information
Tapping Afterpay at a physical counter isn't a different product. It's the same account, used at participating NZ retailers, with contactless payments supported through Apple Pay or Google Pay. Nothing new to sign up for.
The distinction matters because in-store is where the psychology shifts. Online you've got a cart, a total, a moment to think it over. At a counter you've got a queue and a decision made in four seconds.
That's not idle worry. A Consumer NZ survey of 2,000 adults found 55% of BNPL customers said the product encouraged purchases they otherwise would not have made, and 14% had incurred late-payment fees. The fieldwork ran in April and May 2021, so read those as behaviour findings rather than a current market size.
In-store habit worth stealing: decide the purchase before you reach the counter, not at it. If the item wasn't on your list, splitting it into four doesn't make it cheaper.
Works well: small, planned buys at retailers you already trust, with payment dates visible in the app. Works badly: the impulse tap at 5pm on a Friday, three days before payday.
Website: Afterpay New Zealand (afterpay.com/en-NZ)
Pay in 4 is a payment option inside Klarna, not a standalone app. Eligible customers at participating NZ merchants get four instalments, and the terms depend on the merchant and on approval. Two people can see different options at the same checkout.
That's the part worth slowing down for. The MBIE New Zealand Consumer Survey 2026 reports 33% of consumers had used a BNPL agreement, and 88% of BNPL users said they felt confident they understood the agreement sufficiently to make an informed decision.
Confidence and clarity aren't the same thing, mind you. That survey is a different instrument from earlier ones, with different wording, fieldwork dates and samples, so don't line the numbers up against older studies and draw tidy conclusions.
What you should do at checkout is boring and effective. Read the repayment schedule, find the fee triggers, and check the plan fits your next four paydays rather than your best-case one.
Pros: instalments where the retailer supports Klarna, managed alongside purchase and delivery information. Cons: not offered everywhere, not guaranteed for every purchase, and terms vary enough that Klarna's NZ terms are worth reading once properly.
Website: Klarna New Zealand (klarna.com/nz)
| Provider | Current status in NZ | Payment structure | Where it works | Best for |
|---|---|---|---|---|
| Afterpay | Available to eligible customers | Four instalments, generally fortnightly; may be fee-free when paid on time | Participating online and in-store retailers | Broad retailer choice and app-based payment management |
| Klarna | Available to eligible customers at participating retailers | Pay in 4 may be available; options depend on merchant and approval | Participating NZ retailers | An alternative to Afterpay with in-app order management |
| Finley | NZ app-based credit option; applications may not always be open | Revolving credit with a published 60-day interest-free period on eligible purchases; interest may apply after | Participating retailers | Shoppers seeking a local retail credit option |
| Zip NZ (withdrawn) | Withdrawn; not available for new purchases | Formerly Pay in 4; existing customers may manage balances | Existing account management only | Existing customers managing outstanding balances |
| Payright NZ (no new loans) | No longer offers new loans | New loans unavailable | Not available for new purchases | Existing customers checking provider information |
| Laybuy (legacy service; not a separate current option) | Not established as a separate current service; NZ assets acquired by Klarna | No separate current payment structure established | Check for Klarna at checkout | Understanding older Laybuy listings |
| Genoapay (closed) | Closed in NZ | No longer available | Not available for new purchases | Identifying outdated BNPL listings |
| humm NZ (closed) | NZ service closed | No longer available | Not available for new purchases | Identifying outdated BNPL listings |
| Afterpay in-store payments (Afterpay feature, not a separate app) | Available to eligible customers at participating stores | Afterpay instalments; contactless payment via Apple Pay or Google Pay may be supported | Participating NZ retailers | Using Afterpay for eligible in-store purchases |
| Klarna Pay in 4 (Klarna feature, not a separate app) | Available to eligible customers at participating merchants | Four instalments where offered; terms depend on merchant and approval | Participating NZ retailers | Splitting eligible purchases through Klarna |
The most useful BNPL app is the one available at the checkout you use. Afterpay may suit purchases at retailers that offer it; Klarna makes more sense where it is the available instalment option. Keeping both can be convenient, but using multiple accounts at once makes repayments harder to track.
Finley-style revolving credit calls for a different approach. It may suit one larger purchase you can repay within the interest-free period. Using a credit line to cover regular expenses is riskier: instalments have set repayment dates, while revolving balances can linger if you pay only what you can afford each week.
Check the provider's website for information aimed at new customers, then confirm the option appears at the retailer's checkout. A logo on an old comparison page does not mean the service still accepts new purchases. BNPL listings can become outdated as services close, withdraw or become features within another app.
There is also a broader question: how manageable is BNPL in practice? FinCap says consumer protections introduced in September 2024 have not removed concerns about unaffordable repayments, late fees and financial stress. It supports mandatory affordability assessments and tighter controls on late fees.
Most payments may be made on time, while some users still face harm. A successful repayment does not necessarily mean the purchase was affordable, particularly for someone with unstable income or several overlapping accounts.
For founders and retailers, the practical lesson is that provider availability can change, and checkout options may shift as apps and services evolve. NZ Apps is an independent media and directory covering app and tech companies in New Zealand and Australia. NZ and Australian companies can add themselves to the directory or advertise to regional tech decision-makers.
Choose one provider where possible, read its fee schedule, and know what happens if a payment is late. That is more useful than chasing an app that appears free but may be difficult to manage.
BNPL is one part of a changing payments market. NZ Apps helps founders and operators find regional tech companies and software; businesses can browse its directory or add their company through NZ Apps.
Add your NZ or Australian app or tech company to the NZ Apps directory and get discovered by founders and operators across the region.
Get ListedReach tech decision-makers across New Zealand and Australia. Sponsored and dofollow editorial links, permanent featured listings, and sponsored articles on a DA30+ .co.nz domain.
See Options